Table of Contents
Yalla Financial Solutions has received in-principle approval for cross-border payments in the UAE, the company announced on July 27, 2026. The approval, issued by the Central Bank of the UAE (CBUAE) under its Retail Payment Services and Card Schemes Regulation, covers a Retail Payment Services (RPS) Category II license.
An in-principle approval is a conditional step, not a finished license. Yalla still has to complete the CBUAE’s remaining requirements before the RPS Category II license becomes final and the company can operate under it.
Waleed Sadek, CEO and founder of Yalla Financial Solutions, said
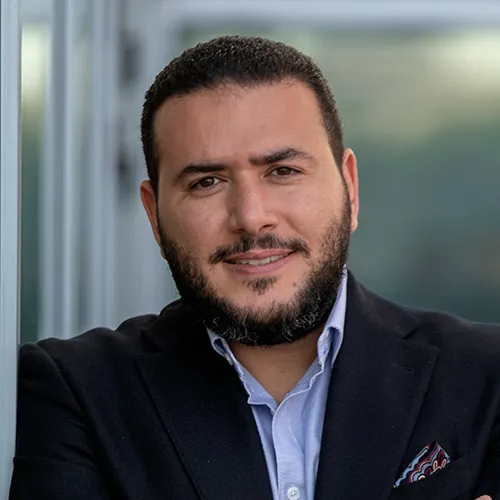
“The approval reflects the company’s commitment to building trusted, secure, and innovative payment infrastructure in the UAE. Yalla looks forward to working with the CBUAE to complete the remaining regulatory requirements and obtain the final Retail Payment Services Category II license.”
A note on the name: Yalla Financial Solutions is not the same company as Yalla Group, the Dubai-based, NYSE-listed voice and social entertainment platform. The two share a common Arabic word (roughly, “let’s go”) but have no corporate relationship. This article covers Yalla Financial Solutions only.
Why this in-principle approval for cross-border payments matters
| Detail | Description |
|---|---|
| Regulator | Central Bank of the UAE (CBUAE) |
| Framework | Retail Payment Services and Card Schemes Regulation |
| License categories | Four tiers, Category I through IV, based on the mix of services a provider offers |
| What separates Category II from Category III | Cross-border fund transfer capability. Adding cross-border transfers moves a provider from Category III to Category II and roughly doubles the minimum capital requirement at the higher tier |
| Services covered under the regulation | Nine service types across the four categories, including payment account issuance, payment instrument issuance, merchant acquiring, payment aggregation, domestic and cross-border fund transfers, payment token services, payment initiation, and payment account information services |
The cross-border distinction matters specifically for Yalla. The company’s Yalla Super App, built in partnership with Visa and unveiled in 2022 by Paysky, the Cairo-founded fintech Sadek also founded, already operates in the UAE, Saudi Arabia and Pakistan, with Kuwait reported as a next market. A Category II license, once finalised, would give Yalla a UAE-licensed basis for the cross-border payment flows a multi-country platform like that needs, rather than routing them through partner banks or third-party rails alone.
Who is behind Yalla
Waleed Sadek founded Paysky in Cairo in 2017 after roles at Visa, where he led innovation and new technology for the Middle East and Africa before managing the company’s strategy team across Central and Eastern Europe, the Middle East and Africa. Paysky and Visa launched the Yalla Card and Yalla Super App in 2022, offering bill payments, online shopping, salary disbursement for employers, and merchant collection tools under the Yalla brand, in addition to Yalla Business services aimed at enterprises. Yalla Financial Solutions is the regulated entity now seeking a formal UAE payments license to operate that platform’s payment flows directly, rather than solely through partner institutions.
Why it matters
For the UAE’s payments market
An RPS Category II license is a meaningful bar to clear precisely because of the cross-border requirement it carries. Domestic-only payment providers can operate under a Category III license at a lower capital threshold; a provider that wants to move money across borders inside a regulated UAE license has to meet the CBUAE’s higher bar. Yalla’s application signals that a platform already live across multiple GCC and South Asian markets wants its cross-border payment infrastructure inside the UAE’s own regulatory perimeter, rather than layered on top of it through intermediaries.
For Yalla’s users and merchants
For businesses and consumers already using the Yalla Super App across its current markets, a finalised Category II license would put Yalla’s own payment rails, rather than third-party partners, behind cross-border transactions the platform already needs to support its UAE, Saudi Arabia, Pakistan and prospective Kuwait footprint. That is a licensing and infrastructure change more than a product change for existing users in the near term; the practical difference shows up once the license moves from in-principle to final and Yalla can point to what specifically runs on it.
The bottom line
Yalla Financial Solutions has cleared the first stage of a UAE payments license built for cross-border activity, which lines up with the multi-country footprint the Yalla Super App already has. What comes next is the harder part: converting an in-principle approval into a full Retail Payment Services Category II license, and then showing what changes in how money actually moves for Yalla’s users once it does.
FAQs
What did Yalla Financial Solutions just receive?
In-principle approval from the Central Bank of the UAE for a Retail Payment Services Category II license, announced July 27, 2026.
Is this a final license?
No. In-principle approval is a conditional step. Yalla still needs to complete the CBUAE’s remaining requirements before the license becomes final.
What does a Category II license allow that a lower category doesn’t?
Cross-border fund transfer services. Category II sits above Category III specifically because it permits moving funds across borders, which comes with a higher capital requirement.
Is Yalla Financial Solutions the same company as Yalla Group, the social entertainment platform?
No. They are unrelated companies that happen to share a common Arabic word in their name.
What is the Yalla Super App?
A platform launched in 2022 by Paysky in partnership with Visa, offering bill payments, shopping, salary disbursement and merchant tools under the Yalla brand, operating in the UAE, Saudi Arabia and Pakistan, with Kuwait reported as a next market.
Editor’s Take: Plenty of UAE fintechs pursue a payments license; fewer specifically need the cross-border tier, because fewer are already running live operations across four countries the way Yalla’s Super App is. That makes this approval read less like a new market entry and more like a company trying to bring infrastructure it already needs in-house, under its own UAE license, instead of renting it from partners. Worth watching whether Yalla talks specifically about what moves onto its own rails once this in-principle approval for cross-border payments converts into a final license, rather than treating it as a generic compliance milestone.